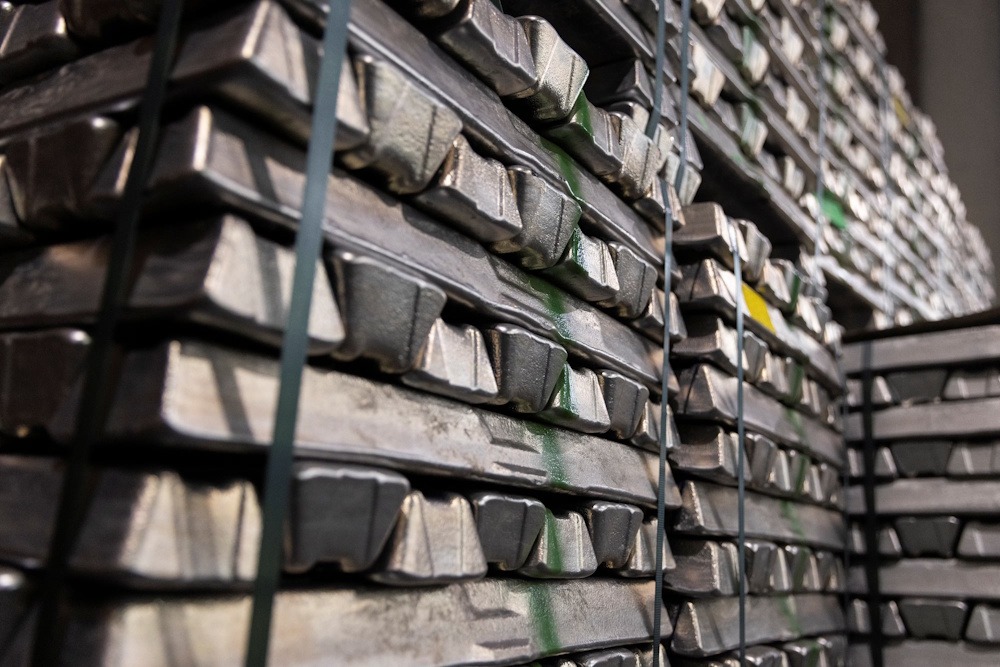
Aluminium prices concluded the trading session with a decline of 0.41%, settling at Rs 326.20. This downward pressure can be attributed to enhanced supply conditions, as Emirates Global Aluminium disclosed that 61% of the reduction cells at its Al Taweelah smelter have resumed operations, alongside a rise in refinery utilisation to around 70%. The recovery in Middle Eastern production has heightened expectations for increased overseas supply, while a robust US dollar and climbing Treasury yields have exerted additional pressure in light of anticipated Federal Reserve rate hikes. However, the downside remained constrained by tight global inventories, as aluminium stocks tracked by the Shanghai Futures Exchange fell by 3% from the previous Friday.
London Metal Exchange inventories were recorded at 226,350 tonnes, reflecting a decline of nearly 56% since January. Meanwhile, the cash-to-three-month premium decreased to $131 per tonne from a 36-year high, suggesting a degree of moderation in the tightness of nearby supply. Global aluminium inventories have decreased to around 44 days of consumption, indicating relatively constrained market conditions. Meanwhile, China’s aluminium exports and aluminium product shipments rose by 18% year-on-year, reaching 5.9 million tonnes during the period from January to October.
In October, China’s primary aluminium production amounted to 3.85 million tonnes, reflecting a year-on-year increase of 1.8%. This brings the cumulative output to 38.85 million tonnes, representing a growth of 3.5%. Production is poised to surpass 46 million tonnes by 2026, bolstered by elevated smelter operating rates. The International Aluminium Institute reported global primary aluminium production of 6.014 million tonnes in September, compared with 6.10 million tonnes a year earlier. Despite the current supply constraints, the anticipation of a rebound in Middle Eastern production alongside a possible global surplus by 2027 may constrain medium-term price increases.
However, Jefferies emphasised that the restarts of Middle Eastern smelters may unfold at a slower pace than anticipated, attributed to elevated alumina import costs and difficult operating economics. Technically, the market is experiencing long unwinding, as open interest has decreased by 2.51% to 3,224 contracts, accompanied by a price decline of Rs 1.35. Aluminium exhibits immediate support at Rs 324.50; a decline below this level may lead prices to test Rs 322.50. Conversely, resistance is established at Rs 328.50. A sustained move above this level could extend the recovery toward Rs 331.00.