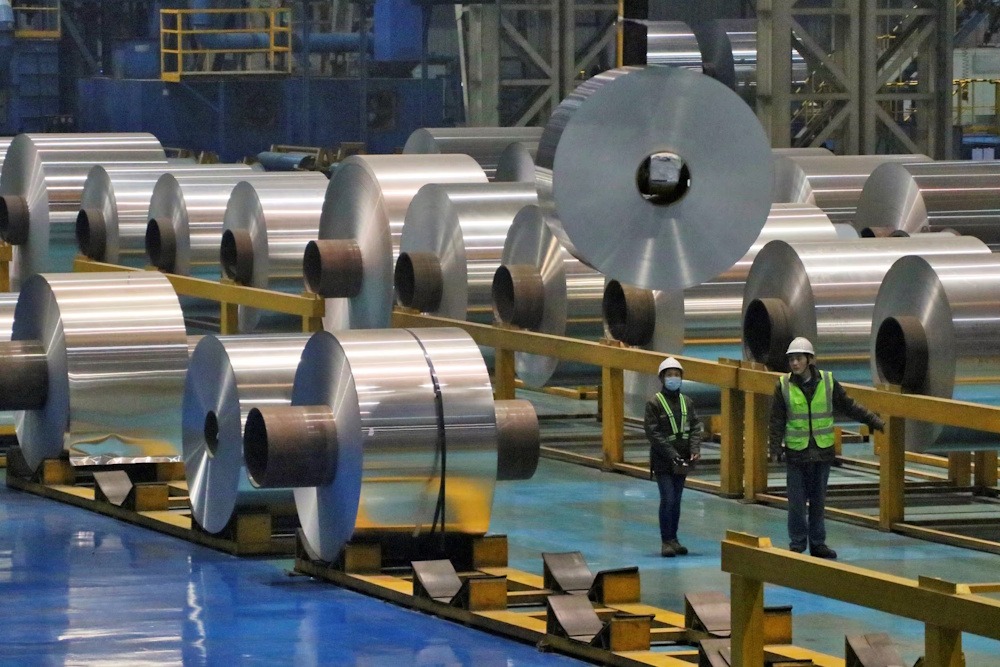
Aluminium concluded the trading session with a decline of 0.56%, settling at Rs 330.3. This downturn was influenced by reports detailing the aggressive overseas expansion strategies of Chinese producers, alongside apprehensions regarding a possible global surplus anticipated in 2027. However, losses were constrained by diminishing exchange inventories and ongoing supply uncertainty. Inventories at the London Metal Exchange decreased to 234,100 tonnes, accompanied by orders to withdraw 3,500 tonnes from registered warehouses in Asia. Stocks monitored by the Shanghai Futures Exchange experienced a decline of 10.2%, reaching 212,858 tonnes. Concurrently, inventories at three major Japanese ports decreased by 9.5% month on month, totalling 223,200 tonnes at the end of September.
Global primary aluminium production experienced a year-on-year decline of 1.4%, totalling 6.014 million tonnes in September, underscoring the ongoing supply-side challenges. However, China sustained elevated production levels, with third-quarter primary aluminium output increasing by 2.2% year on year to 11.84 million tonnes. Production during the first nine months rose by 3.8% to 35.03 million tonnes, bolstered by robust smelting margins and operational efficiencies, notwithstanding the capacity ceiling imposed by the government. Supply concerns have diminished as Emirates Global Aluminium has resumed operations at 631 of its 1,262 reduction cells at the Al Taweelah smelter, thereby restoring 50% of its capacity. Full production is anticipated by the first quarter of 2027.
Meanwhile, the expansion of Indonesian capacity alongside the enhancement of supply flows from the Gulf is anticipated to bolster global availability. The aluminium market may encounter a surplus surpassing 1 million tonnes by 2027, driven by the influx of new production into the market. Japanese buyers have consented to pay premiums of $255 per tonne for shipments scheduled between October and December, marking a 35% decrease from the preceding quarter, indicative of evolving regional supply dynamics. A stronger and cautious outlook ahead of the Federal Reserve’s policy decision also weighed on sentiment.
Technically, the market is experiencing new selling activity, as open interest has increased by 6.55% to 4,523 contracts, accompanied by a price decline of Rs 1.85, which suggests the establishment of new short positions. Aluminium exhibits support at Rs 328; a decline beneath this threshold may lead prices to test Rs 325. Conversely, resistance is identified at Rs 333.50, with a sustained advance beyond this point likely propelling prices toward Rs 336.50.