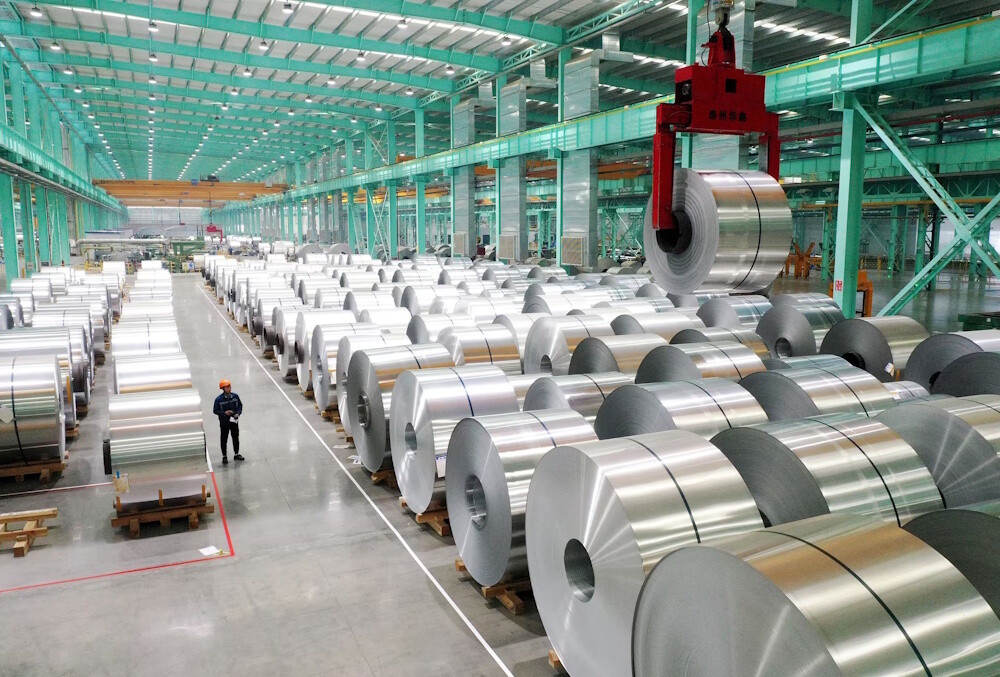
Aluminium prices increased by 0.11% to close at Rs 329.80, bolstered by a significant drop in warehouse inventories on the Shanghai Futures Exchange, which decreased by 10.3% from the prior week to 212,858 tonnes. However, gains remained constrained due to a robust US dollar and apprehensions regarding a possible global supply surplus in 2027. Supply conditions are gradually improving, as Emirates Global Aluminium has restarted 631 of its 1,262 reduction cells at the Al Taweelah smelter, thereby restoring 50% of its capacity. Full production is anticipated by the first quarter of 2027.
Meanwhile, China sustained elevated smelting rates, with primary aluminium production increasing by 3.1% year-on-year to 3.91 million tonnes in September, while third-quarter output rose by 2.2% to a record 11.84 million tonnes. Production from January to September totalled 35.03 million tonnes, reflecting a year-on-year increase of 3.8%, which underscores robust domestic supply in the face of a persistent capacity ceiling. Globally, aluminium production faced ongoing challenges, as data from the International Aluminium Institute indicated that primary output in September decreased to 6.014 million tonnes, down from 6.10 million tonnes in the same month of the previous year.
However, expectations of additional supply from Indonesia and the recovery of Gulf smelters are exerting downward pressure on the medium-term outlook. In August, Indonesian aluminium exports surpassed 150,000 tonnes, coinciding with the relaxation of shipping restrictions through the Strait of Hormuz, which has enhanced the outlook for a recovery in Gulf supply. Analysts anticipate that the global aluminium market will transition into a surplus exceeding 1 million tonnes by 2027. Japanese buyers have consented to pay premiums of $255 per tonne for shipments scheduled between October and December, reflecting a 35% decrease from the preceding quarter, which suggests a reduction in supply apprehensions.
Overall, the reduction in exchange inventories coupled with persistent supply disruptions offers short-term support, whereas the increase in Chinese production and anticipated capacity expansions in Indonesia and the Gulf may constrain prices in the medium term. Technically, the market is experiencing new buying activity, with open interest rising by 0.16% to 4,478 contracts, accompanied by a price increase of Rs 0.35, suggesting the establishment of fresh long positions. Aluminium is presently encountering support at Rs 328, beneath which prices may test Rs 326. On the upside, resistance is positioned at Rs 332, and a sustained movement above this level could drive prices toward Rs 334.