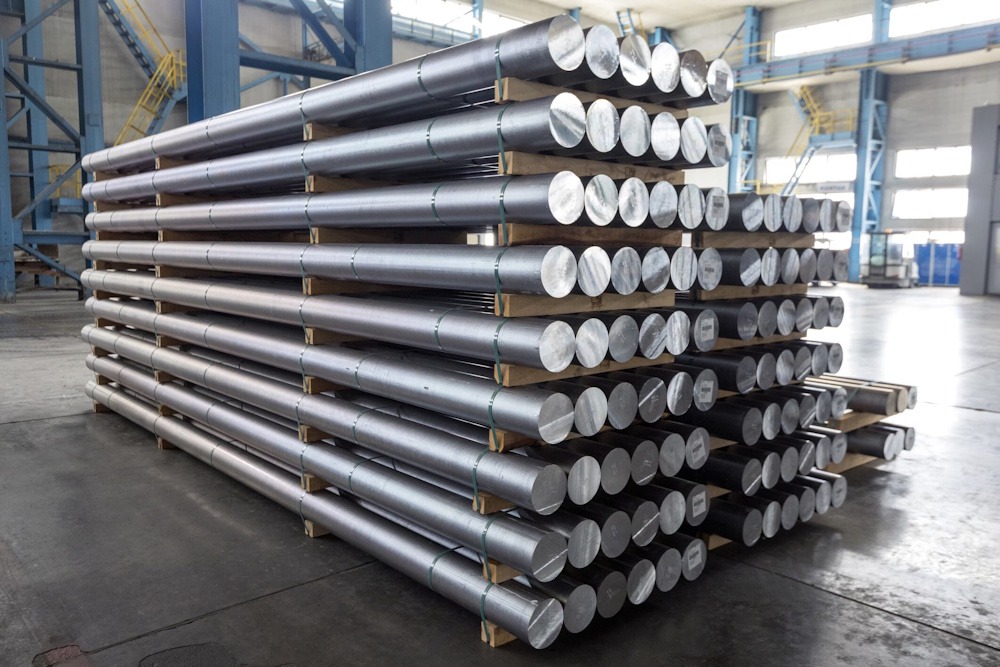
Aluminium concluded the session with a decline of 0.51%, settling at Rs 339.65. This downturn was influenced by diminishing worries regarding supply disruptions in the Gulf and anticipations of increased production capacity in Indonesia. Additionally, a stronger dollar and the rise in global bond yields contributed to the negative sentiment. However, the downside remained constrained as enhancing demand expectations and alleviated concerns regarding interest rates offered support. Japanese aluminium buyers have consented to premiums of $255 per tonne above benchmark prices for shipments scheduled from October to December, marking a 35% decrease from the prior quarter. This adjustment indicates a reduction in regional supply concerns.
Macquarie has revised its 2026 global aluminium deficit forecast down to 820,000 tonnes, a decrease from the prior estimate of 940,000 tonnes. This adjustment is attributed to the quicker-than-anticipated restarts of smelters in the Middle East. Furthermore, the firm anticipates that the market will transition into a surplus of 410,000 tonnes by 2027. EGA has resumed operations at 25% of its Al Taweelah smelter following damage incurred from an Iranian attack, whereas Rio Tinto has successfully ensured the continuation of operations at Bell Bay Aluminium until 2031. Chinese aluminium exports experienced a year-on-year increase of 17.2% in August, driven by a backdrop of muted domestic demand and high inventory levels. Concurrently, Japanese port stocks saw a month-on-month rise of 22.7%, reaching 246,600 tonnes.
Global aluminium production experienced a year-on-year decline of 1.5% in August. Notably, output from the GCC fell sharply by 43%, totalling 299,000 tonnes. In contrast, China’s production increased by 3%, reaching a record high of 3.87 million tonnes. SHFE aluminium inventories decreased by 57,244 tonnes, while LME stocks saw a reduction of 15,575 tonnes, suggesting a contraction in international supply. In July, China’s exports of unwrought aluminium and semis experienced an 18.6% year-on-year increase, totalling 643,000 tonnes. For the period from January to July, exports rose by 16.7%, reaching 4.04 million tonnes.
Alcoa has adjusted its 2026 alumina production guidance downward to a range of 9.5-9.6 million tonnes, citing operational disruptions in Western Australia as the cause. From a technical perspective, the market is experiencing long liquidation, evidenced by a 1.08% decrease in open interest to 4,785, alongside a price decline of Rs 1.75, which suggests an unwinding of positions. Aluminium exhibits support at Rs 338.10; a persistent breach beneath this threshold may result in a decline to Rs 336.50. On the upside, resistance is positioned at Rs 341.70, and a decisive move above this level could lead to further gains toward Rs 343.70.