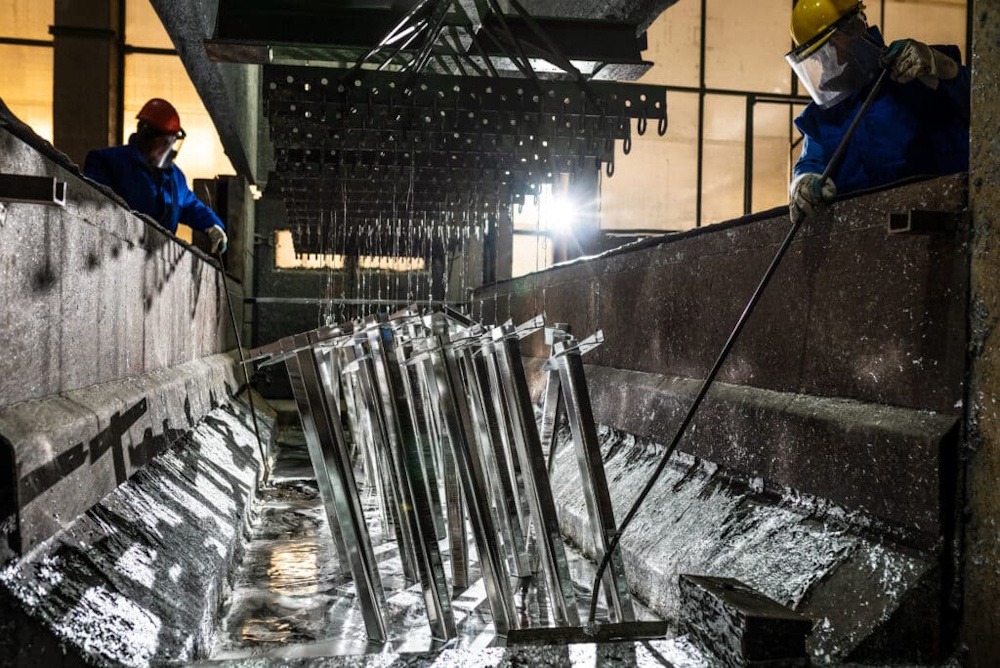
Zinc prices declined 0.76% to settle at Rs. 410.35, influenced by expectations of recovering Chinese mine production and improved concentrate availability, which may gradually alleviate supply tightness. Nevertheless, the downside appeared constrained due to the tightening of global mine supply, a decrease in refined production, and apprehensions regarding potential disruptions at significant smelters. Operational challenges at Korea Zinc, Glencore’s Kazzinc, and YoungPoong’s Seokpo smelter have heightened apprehensions regarding possible supply disruptions. Meanwhile, the uncertainty surrounding Nyrstar’s unprofitable Budel smelter in the Netherlands further exacerbates supply risks in the West.
In October 2026, China’s refined zinc production experienced a month-on-month decline of 3.5% and a year-on-year decrease of 12%. Additionally, the cumulative output from January to October fell by 1.5% compared to the previous year, falling short of expectations.However, November refined production is projected to increase by 4.6% month-on-month, attributed to maintenance recoveries and production ramp-ups at various smelters. Nonetheless, output is anticipated to be 4.8% lower compared to the same period last year. China’s manufacturing activity demonstrated resilience, as evidenced by the RatingDog Manufacturing PMI registering at 52.0 in October, signifying the eleventh consecutive month of expansion.
Meanwhile, zinc inventories monitored by the Shanghai Futures Exchange decreased by 6.3% from the previous Friday, underscoring a contraction in domestic supply. Western refined zinc production experienced a decline of 3.4% year-on-year during the first half of 2026, influenced by high energy costs and constrained availability of raw materials. The International Lead and Zinc Study Group reported that the global refined zinc market experienced a deficit of 3,900 tonnes in August, contrasting with a surplus of 27,500 tonnes in July. However, the January-August period continued to show a surplus of 96,000 tonnes.
Looking ahead, the ILZSG anticipates a transition in the global market to a surplus of 25,000 tonnes by 2027, following an estimated deficit of 88,000 tonnes in 2026. This shift is underpinned by a projected 2% increase in refined production alongside a 3% rise in mine output. Global demand is anticipated to increase by 1.2%, reaching 14.19 million tonnes by 2027. Technically, zinc is experiencing long unwinding, as open interest has decreased by 1.34% to 1,549 contracts, coinciding with a price decline of Rs. 3.15. Support is positioned at Rs. 409.00, with an additional level at Rs. 407.50. Conversely, resistance is identified at Rs. 413.00, beyond which prices may approach Rs. 415.50.